FRTB Market Risk · HFT · Low-Latency C++ · FPGA/DPDK · Automated Market Making · Statistical Arbitrage · Machine Learning
Quantitative Developer and Researcher based in New York, engineering ultra-low latency trading infrastructure and alpha-generating strategies for hedge funds, proprietary trading, and high frequency trading environments. Currently a Senior Quantitative Developer at Barclays, building C++ and Python FRTB market risk engines for Basel IV capital across the Internal Model Approach (IMA) and Standardised Approach (SA). Previously a C++ Quantitative Developer at BNP Paribas CIB (Automated Market Making), building low-latency components of the market-making stack for the Prime Credit Market (average $500M daily market-making volume). Previously contributed to systematic merger-arbitrage strategies at an $8.5 Billion AUM fund and engineered FICC trading services at Bank of America, reducing trade processing latency by 50%. Expertise spans the full stack of modern quantitative finance: FPGA-accelerated market data handlers, kernel bypass (DPDK), lock-free C++ execution engines, stochastic calculus-based derivative pricing, and ML-driven risk and execution frameworks.
- Georgia Institute of Technology (Online): M.S. in Computer Science (Specialization in Computing Systems) | Aug 2024 - Expected Dec 2026
- Stevens Institute of Technology: M.S. in Financial Engineering (GPA: 3.974/4.0) | Aug 2024 - May 2026
- WorldQuant University: M.S. in Financial Engineering (GPA: 86%) | Dec 2021 - May 2024
- Carnegie Mellon University (Tepper): M.S. in Computational Finance (Program withdrawn due to father's illness) | Aug 2021 - Oct 2021
- Vellore Institute of Technology: B.Tech in Computer Science and Engineering (GPA: 8.78/10.0) | Jul 2014 - Sept 2018
Barclays | Senior Quantitative Developer (Contract), FRTB Market Risk
Oct 2026 - Present | New York, USA (Hybrid)
Optimizing enterprise-scale analytics engines and distributed calculation pipelines supporting the Fundamental Review of the Trading Book (FRTB) across the Corporate & Investment Bank. Leading technical delivery of Basel IV market risk capital models across the Internal Model Approach (IMA) and Standardised Approach (SA).
- Engine Architecture & HPC: Architecting low-latency C++ and Python distributed pricing and risk calculation pipelines, optimizing Expected Shortfall (ES), Default Risk Charge (DRC), and Non-Modellable Risk Factor (NMRF) simulations across multi-asset trading desks.
- Sensitivities & SA-TB: Engineering high-throughput aggregation engines for the Sensitivities-Based Method (SBM), Gross Jump-to-Default (JTD), and Residual Risk Add-on (RRAO).
- IMA & P&L Attribution: Designing automated backtesting and P&L Attribution (PLA) test suites (Risk-Theoretical vs. Hypothetical P&L), establishing stable model eligibility pipelines and minimizing capital charge penalties across major trading desks.
- Large-Scale Data Architecture: Scaling real-time scenario generation and risk factor time-series pipelines across high-performance grids, integrating kdb+/q and distributed message queues to ingest multi-terabyte tick and pricing feeds for risk factor observability.
- Model Validation & Governance: Partnering with Quantitative Research, Front Office Trading, Risk Methodology, and Model Risk Governance to implement, validate, and document Basel IV compliance frameworks for regulatory audits (Fed, PRA, FINMA).
- Tech Stack: C++20, Python (NumPy, SciPy, Polars), kdb+/q, HPC grids (Slurm, IBM Symphony), multi-threading/SIMD, Docker, OpenShift/Kubernetes, Git, CI/CD.
BNP Paribas CIB | C++ Quantitative Developer (Co-op), Automated Market Making
Feb 2026 - May 2026 | New York, USA
- Built low-latency components of the automated market-making stack for the Prime Credit Market (average $500M of daily market-making volume), spanning real-time market-data ingestion, tick analytics, and pricing/execution paths.
- Profiled and optimized the software hot path feeding FPGA-accelerated market-data handlers and quoting engines.
- Integrated secure on-premise LLM tooling with Git/Jira/Confluence to automate code, testing, and documentation workflows.
LogiNext Solutions Inc. | Senior Software Engineer, Analytics
Mar 2023 - Jul 2024 | Mumbai, India
- Architected Map Construction, Map Routing, and Rich Vehicle Routing algorithms (3 nested NP-Hard problems) using CP-SAT constraint programming and convex optimization over PostGIS, MongoDB, and S3.
- Led a 12-engineer team delivering a high-throughput geospatial mapping application platform.
- Built an LLM-powered debugging and query-resolution tool used company-wide, cutting mean bug-resolution time by 80%.
Versor Investments (QR Systems LLP) | Quantitative Developer, Merger Arbitrage & Stock Selection
Feb 2022 - Oct 2022 | Mumbai, India
- Developed and backtested systematic merger-arbitrage strategies for an $8.5 Billion AUM fund, improving alpha capture by 15%.
- Built and deployed ML pipelines for Order and Execution Management Systems, increasing trade execution efficiency by 29%.
- Designed an ESG-driven merger-arbitrage signal capitalizing on pre- and post-merger statistics.
Bank of America | Senior Software Engineer, FICC
Jan 2020 - Jul 2021 | Chennai, India
- Engineered Python-based trading services enhancing storage, processing, matching, and execution of trades on QUARTZ.
- Integrated C++ pipelines with the object-oriented database SANDRA, reducing trade processing latency by 50%.
- Led the migration of 1 million+ lines of code to Python 3.8, enhancing scalability and execution efficiency by 40%.
Bank of America | Senior Tech Associate, Data Analysis and Insight Technology
Jun 2018 - Dec 2019 | Chennai, India
- Architected an ML/AI platform for deploying predictive models, increasing decision-making accuracy by 67%.
- Designed ML models for data validation rules prediction, reducing manual workload by close to 36 Full-Time Equivalents (FTEs).
- Mathematics & Statistics: Probability, Stochastic Calculus, Differential Equations, PDE, Linear Algebra, Numerical Methods, Markov Chains
- Quantitative Finance: Statistical Analysis, Derivative Pricing, Time Series Analysis, Factor Modeling, Predictive Modeling, Greeks, Market Microstructure, FRTB (IMA/SA), Basel IV Market Risk, Expected Shortfall, P&L Attribution
- Machine Learning: Linear Regression, Clustering, Random Forest, XGBoost, RNN, LSTM, Deep Learning, Neural Networks, NLP, LLMs
- Programming: C++ (17/20/23, primary), Python, C, Java, R, MATLAB, JavaScript, Node.js, ReactJS, NumPy, Pandas, Polars, SciPy, Keras, PyTorch, TensorFlow, Scikit-learn, QuantLib, Statsmodels, CVXPY, OpenMP, MPI, CUDA, Bash
- Data Engineering: Airflow, Dask, Spark, PySpark, FastAPI, Kafka, Flink, SQL, BQL, KDB+/Q, PostgreSQL, MongoDB, ZeroMQ, Cassandra, Redis, Hadoop, HDFS
- Systems & Low Latency: TCP/IP, UDP, Multicast, cache and multithreading optimization, SIMD, FPGA (Verilog, VHDL), kernel bypass (DPDK), lock-free data structures, HPC grids (Slurm, IBM Symphony)
- Cloud & DevOps: Linux, Git, Jenkins, CI/CD, Ansible, Docker, Kubernetes, OpenShift, Helm, AWS, GCP
Oct 2025 - May 2026
- Engineered a sub-10us low-latency trading system with a custom-built limit order book, FPGA market data handlers, kernel bypass (DPDK), hardware timestamping, and lock-free data structures for deterministic, microsecond-level execution.
May 2026 - Jul 2026
- Architected a local-first, autonomous agentic AI platform orchestrating LLM providers behind a unified API, enabling agents to autonomously execute multi-step tool-calling workflows via the Model Context Protocol (MCP) with zero data leaving the host.
- Developed a RAG and persistent semantic-memory system on ChromaDB using high-dimensional vector embeddings for low-latency retrieval, plus a hardware-aware layer that deploys quantized open-weight models.
May 2026 - Jul 2026
- Architected a cross-platform agentic AI developer platform on NixOS with declarative configuration, version-pinned dependencies, symlink-managed files, and automated health checks to bootstrap a complete local AI engineering environment on clean machines.
- Integrated multi-agent orchestration and agent-native CLI workflows automating isolated Git worktrees, autonomous task execution, CI-gated shipping, overnight runs, and upstream synchronization.
Sept 2025 - Dec 2025
- Developed an adaptive volatility regime-switching framework dynamically selecting among passive, TWAP, and aggressive execution strategies.
- Achieved a 20.0% increase in Sharpe Ratio, 6.1% transaction cost reduction, and 20.1% CVaR decrease with robust risk management.
Jun 2025 - Aug 2025
- Designed and backtested a 120-day volume-momentum-based crypto portfolio strategy, yielding a 155.76% annualized return and 1.94 Sharpe Ratio (post transaction costs), significantly outperforming the Bitcoin buy-and-hold benchmark.
Mar 2024 - Jun 2024
- Built a real-time portfolio optimization system using convex and non-convex optimization, enhancing risk-adjusted returns via adaptive asset rebalancing and multi-factor modeling across interest rate, FX, credit, and market risks.
Apr 2022 - Jun 2022
- Developed an ESG strategy converted into a standalone portfolio and embedded across all existing portfolios, capturing the arbitrage opportunity created by ESG scores on target and acquirer pre- and post-merger statistics.
- 1st Place - Vanguard ETF Trading Challenge (personal portfolio).
- President - Stevens Graduate Financial Association.
- Beta Gamma Sigma Member - International business honor society.
- Global Recognition Gold Award (Bank of America) - Led enterprise-wide AI/ML campaign identifying 64 high-impact use cases; delivered AI/ML lectures to 2500+ employees across 4 large-scale events.
- Global Recognition Silver Award (Bank of America, 2x) - Total Return Swap contributions (Post Trade Processing) and an end-to-end in-house AI/ML framework.
- State Rank Holder - International Science Olympiad and International Mathematics Olympiad.
- CFA Level 1
- Bloomberg Market Concepts (BMC)
- Financial Engineering and Risk Management Part I & II (Columbia/Coursera)
- Investment Foundations Program (CFA Institute)
- The Complete Financial Analyst Training & Investing Course
- Machine Learning for Trading Specialization (Google Cloud/NYIF)
- Investment Management Specialization (Geneva/UBS)
- Trading Strategies in Emerging Markets Specialization (ISB)
- Finance & Quantitative Modeling for Analysts (Wharton)
- Corporate Finance and Valuation (NYU Stern, Aswath Damodaran)
- Deep Learning Specialization (Andrew Ng/Coursera)
- Applied Data Science with Python Specialization (Michigan)
- Data Science Foundations using R Specialization (Johns Hopkins)
- Data Science Statistics and Machine Learning Specialization (Johns Hopkins)
- Big Data Specialization (UC San Diego)
- Data Structures and Algorithms Specialization (Coursera)
- Algorithms, Part I & II (Princeton)
- Interests: Chess, Poker, F1, Martial Arts, Cricket, Boxing, Badminton, Reading, Cooking, Dancing, Psychology, History, Philosophy.
- Languages: English, Hindi (Fluent); French, Sanskrit, Spanish, Russian (Intermediate); Chinese, Italian, Tamil, Punjabi (Beginner).
This repository also powers www.shreejitverma.com (Next.js 16, Tailwind CSS v4, deployed on Vercel).
npm run dev          # local dev server
npm run build        # production build
npm run lint         # ESLint
npm run typecheck    # TypeScript strict check
npm run test:e2e     # full Playwright E2E suite (desktop + mobile)
The E2E suite (e2e/) covers every public page; e2e/README.md lists what each spec checks.
CI runs lint, typecheck, and the full suite on every pull request (.github/workflows/e2e.yml).
scripts/enrich_books.py enriches the reading-list dataset with cover images and descriptions from Open Library and Google Books; it is resumable and idempotent.
scripts/import_vault_covers.py imports curated covers from the Obsidian vault (Reading/Library/ notes and Attachments/Covers/) as 320px WebP files under public/covers/, matching books by title and author and never guessing: ambiguous matches, generated title-card covers, and titles listed in scripts/cover_overrides.json are skipped.
Adding a title to that skip list also clears a vault cover it already received, so enrich_books.py fetches a hotlinked one on its next run.
Vault covers take precedence over the hotlinked covers from enrich_books.py, which never overwrites an existing cover; rerun the import after adding books or covers to the vault (python3 scripts/import_vault_covers.py --dry-run previews the changes).
scripts/make_icons.py renders the "SV" monogram site icons (app/favicon.ico, app/icon.png, app/apple-icon.png); rerun it with uv run --with pillow python3 scripts/make_icons.py after changing the theme's primary color.
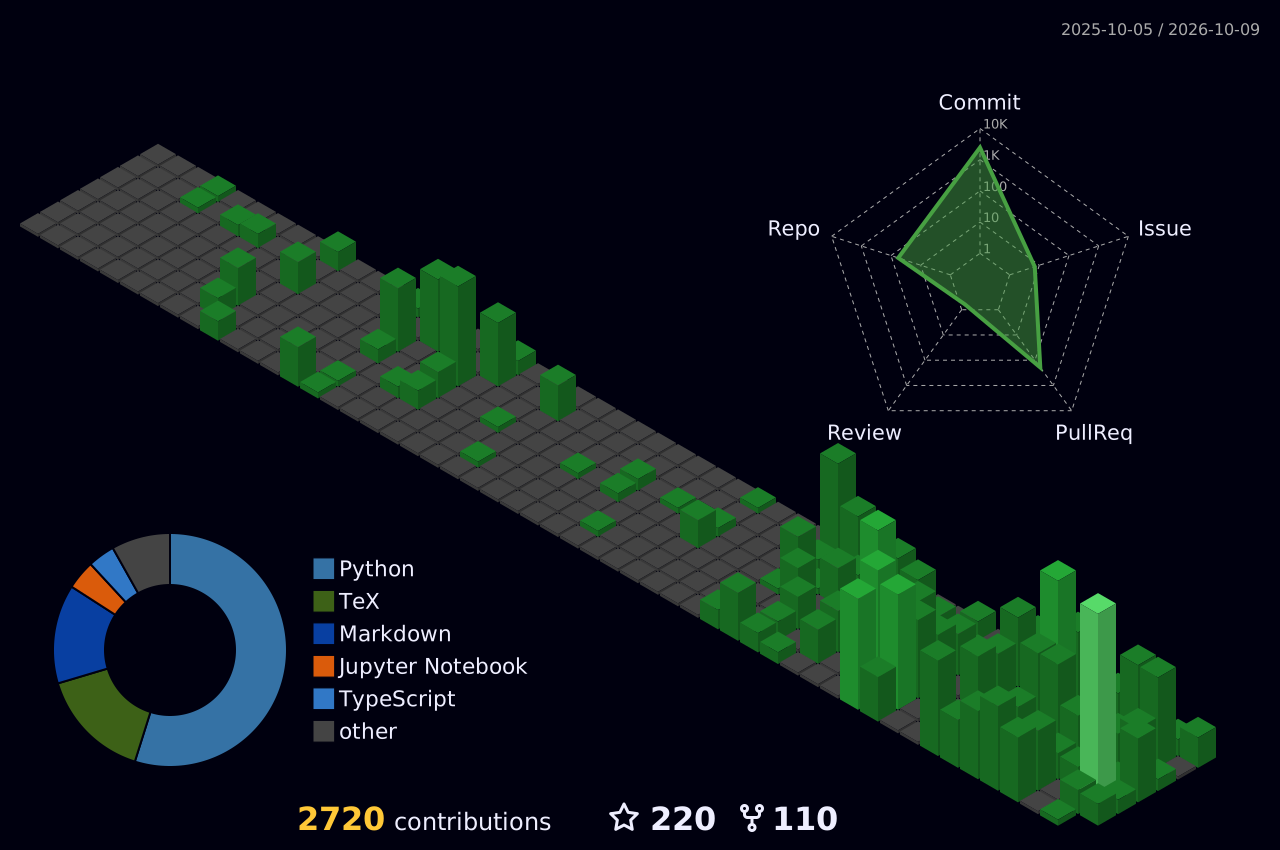
.github/workflows/metrics.yml refreshes the GitHub Impact cards daily and publishes them to the output branch: scripts/github_stats.py writes github-stats.json (rendered natively on the home page), scripts/github_cards.py draws the README's stats and language cards from it, and python3 -m unittest discover -s scripts/tests tests both.
scripts/categorize_books.py assigns book categories through hand-curated overrides (scripts/category_overrides.json), title-family regex rules, and ordered keyword rules, keeping the General shelf a small miscellany bucket.
scripts/ also holds standalone personal data tooling unrelated to the site, such as scripts/amazon_ir_scraper.py, which downloads Amazon investor-relations PDFs (annual reports, proxy statements, shareholder letters) into ~/Downloads/Amazon_IR_Documents.
backlog.md is the workspace task backlog managed by tasks-axi.
Refreshed daily by .github/workflows/metrics.yml from the GitHub API, including private-repository activity.


Website | LinkedIn | Google Scholar | Calendly | Twitter | YouTube
If you find my research or code helpful, consider starring my repositories.